
NEW YORK: Oil prices fell in jittery trading yesterday, as the strengthening dollar and signs of a slowing economy outweighed inventory drops and the Organization of Petroleum Exporting Countries’ (OPEC) cutback of excess production.
The US Energy Department’s Energy Information Administration (EIA) said that crude inventories fell by 5.9 million barrels last week compared to the previous week, and that gasoline inventories fell by 6.5 million barrels. The EIA also reported, however, that inventories of distillates — which include heating oil and diesel fuel — fell by a lower-than-anticipated 1.2 million barrels.
Refineries were running at a low 78.3 percent of their capacity last week, the report said.
“It’s being seen as somewhat aberrant because of the storms,” said John Kilduff, senior vice president of risk management at MF Global LLC. “But I don’t think you can ignore this data.”
Light, sweet crude for October delivery fell $1.11 to $102.15 a barrel in late morning trading on the New York Mercantile Exchange, after initially jumping on the EIA’s report. The contract fell by more than $3 a barrel in the previous session to the lowest close since April 1.
In London, October Brent crude fell $1.41 to $98.93 a barrel on the ICE Futures exchange.
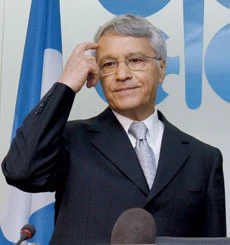
A statement issued by OPEC President Chakib Khelil after his meeting with oil ministers early yesterday noted that the organization agreed to produce 28.8 million barrels a day. Khelil said that quota in effect meant that member countries had agreed to cut back 520,000 barrels a day in production over the established quota.
OPEC, however, decided not to take the more dramatic step of slashing its production target. The move was viewed as a compromise meant to avoid a backlash from the biggest petroleum-consuming nations and stop the rapid decline in oil prices. A number of analysts said they did not expect OPEC’s output decision to spark a sustained rally in oil prices, as investors remain concerned over slowing economic growth in the US, Europe and Japan.
The EIA report showed that demand for gasoline, distillate fuel and jet fuel over the past four weeks was below year-ago levels.
“You just can’t fight the weight of the market right now,” said Darin Newsom, senior analyst at DTN in Omaha, Nebraska. “I still think we’re going to drop below $100.”
The US Department of the Interior’s Minerals Management Service said that, as of Tuesday, about 77.5 percent of oil production and about 64.8 percent of natural gas production in the Gulf remained shuttered.
Oil and gas operators have been working to restore production since they prepared for Hurricane Gustav nearly two weeks ago.
In other Nymex trading, heating oil futures fell 1.23 cents to $2.8888 a gallon, while gasoline prices gained 01 cents to $2.6424 a gallon. Natural gas for October delivery fell 8.5 cents to $7.450 per 1,000 cubic feet.
Meanwhile, White House spokesman Scott Stanzel said, “We need more supplies on the market, not less. Energy prices are still very high, despite their recent decline.”
We “certainly disagree” with that decision, said White House spokeswoman Dana Perino who also urged lawmakers in the US Congress to complete legislation aimed at fostering the production of more energy resources.
“We’d like to have more supply that we produce here, they have some legislation that’s in front of them that would be comprehensive,” Perino told reporters. “We are looking for a comprehensive energy package that can help us add more supply to the market and diversify the supply at the same time.”