
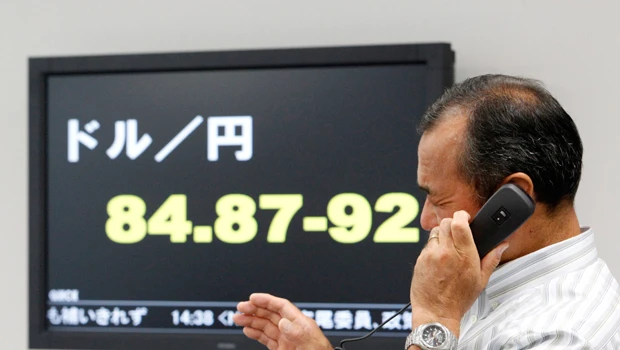
- NEW YORK: The dollar slumped against other major currencies and global shares declined on Wednesday after the Federal Reserve opened the door to more monetary easing, signaling the depth of its concern over weak growth.
Gold hit a record high amid speculation that US government stimulus would quicken inflation, while the prospects of more cash flowing through the system boosted stocks and currencies in developing economies that are outperforming Europe and the United States.
The Fed said on Tuesday it stood ready to pump new dollars into the economy - a second round of so-called quantitative easing. The central bank made no policy shift, but investors, interpreting the statement as more easing was on the way, took profits in stocks built so far this month, analysts said.
European and Wall Street shares drifted lower as investors were torn between expectations for Fed help and its message of a faltering economic recovery. They were also uncertain if Fed moves would be enough to ward off a double-dip recession.
The Dow Jones Industrial Average dropped 45.67 points, or 0.42 percent, to 10,715.36. The Standard & Poor's 500 fell 7.28 points, or 0.64 percent, to 1,132.50. The technology-heavy Nasdaq Composite lost 24.29 points, or 1.03 percent, to 2,325.06.
In Europe, the FTSEurofirst 300 index dropped 1.5 percent, while the MSCI world equity index rose 0.1 percent, boosted by Asian and other emerging market shares as emerging market stocks rose 0.5 percent.
The Thomson Reuters global stock index declined 0.4 percent.
The dollar fell 0.6 percent to a six-month low against a basket of major currencies.
The euro rose as high as $1.3440, its strongest since April, as traders believing in the success of Fed stimulus took on risk. At midday in New York, the euro gained 1 percent to $1.3384. Against the Japanese yen, the dollar fell 0.81 percent to 84.40 yen.
The sliding dollar helped gold, which rose to a record high above $1,296 an ounce before easing to $1288.10.
The precious metal surged as high as $1,296.30 an ounce in afternoon trade on the London Bullion Market, extending its record-breaking run.
On the back of gold's run higher, sister metal silver struck the highest levels for two and a half years, at $21.15 an ounce.
Oil prices slid Wednesday after the government said stockpiles of oil and gasoline grew last week, even though a major pipeline serving Midwest refineries was shut because of a leak.
Benchmark crude for November delivery lost 70 cents at $74.27 a barrel in midday trading on the New York Mercantile Exchange.
The gains in crude and gasoline supplies surprised many traders and analysts who expected a drop because of the closed Enbridge Energy Partners pipeline that carried Canadian crude to refineries in Wisconsin and Indiana. The pipeline restarted Friday, eight days after it was closed because of a leak.
The Energy Department's Energy Information Administration said commercial crude inventories increased by 1 million barrels to 358.3 million barrels for the week ending Sept. 17. Analysts expected a drop of 1.5 million barrels, according to Platts, the energy information arm of McGraw-Hill.
Gasoline supplies rose by 1.6 million barrels to 226.1 million barrels. Gasoline demand over the four weeks ended Sept. 17 averaged 9.1 million barrels a day, down 0.1 percent from the same period of 2009. Demand fell from the previous week by 172,000 barrels a day to 8.8 million barrels a day.
In other Nymex trading in October contracts, heating oil fell 2.45 cents to $2.0945 a gallon and gasoline lost 2.95 cents at $1.8901 a gallon. Natural gas rose 1.5 cents to $3.934 per 1,000 cubic feet.
In London, Brent crude fell 67 cents to $77.75 a barrel on the ICE Futures exchange.