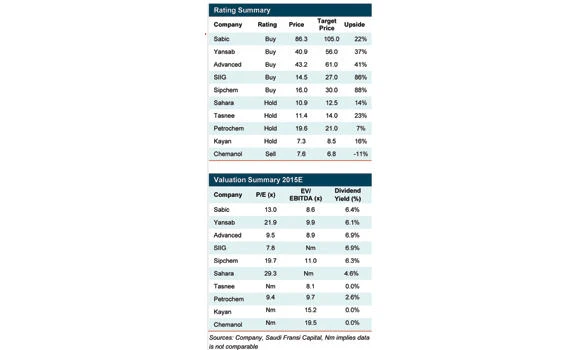
JEDDAH: Saudi Arabia’s petrochemical companies to start reporting Q4, 2015 earnings in the coming days. For the 10 companies, Saudi Fransi Capital expects a combined Q4, 2015 net profit of SR5 billion implying 23 percent q/q and 14 percent y/y declines.
While 9 out 10 companies should post sequential declines of varying magnitude, decline for Advanced/Petrochem at 16 percent q/q is expected to be at the lower end in the sector. While it expects Saudi Kayan Petrochemical Co. to generate net profit after three consecutive losses, net profit of SR73 million on a revenue base of SR2.1 billion is largely inconsequential. Given a volatile product price environment, while earnings volatility is unsurprising, it can be exacerbated by plant shutdowns in case of Saudi Industrial Investment Group, Saudi International Petrochemical Co. and Methanol Chemicals Co. (Chemanol). Furthermore, due to decline in crude price over the previous 6 months, balance sheets may be carrying some higher cost inventory. Since this is the last quarter of the year, Saudi Fransi Capital would not be surprised to see some inventory writedowns. In this note, while Saudi Fransi Capital maintains Buy rating on Saudi Basic Industries Corp. (SABIC), Advanced Petrochemical Co., Yanbu National Petrochemical Co., Saudi International Petrochemical Co. and SIIG, it maintain Hold rating on National Petrochemical Co., Sahara Petrochemical Co., National Industrialization Co. and Kayan and Sell rating on Chemanol.
Saudi Fransi Capital sees Advanced as the best positioned among KSA petchem players in a low oil price environment. It has a resilient pass-through model as 100 percent of its feedstock is oil based (30 percent discount to market) meaning a fall in crude oil price lowers its feedstock cost (around 85 percent of cash cost base) and to a large extent offsets the decline in product prices.
According to Saudi Fransi Capital estimates, while +/-5 percent change in crude price impacts valuation by +/-7 percent at the sector level, it impacts Advanced’s valuation by only 2.5 percent.
Saudi Fransi Capital’s analysis suggests that in Q4, 2015, tracking 13 percent decrease in Brent crude price (Q4, 2015 average of 47 a barrel vs. $54 a barrel in Q3, 2015), prices of 12 key petrochemical products (mostly in Asia) on average decreased 13 percent q/q and 25 percent y/y, respectively.
Asian Ethylene price remained largely flat q/q.
After an underperformance in Q3, 2015, petrochemical stocks outperformed Tadawul in Q4, 2015 despite lower crude price and lower product prices.
While Tadawul decreased 5 percent in Q4, 2015, Tadawul petrochemical index was largely flat. Comparing Tadawul petchem with global peers, Saudi Fransi Capital sees KSA petrochemical stocks largely underperformed global peers by varying magnitude.
While Tadawul petrochemical index was largely flat, North American, European and Asian peers were up 9 percent, 9 percent, and 13 percent, respectively.
Tadawul Petchem is trading at 13.6x P/E which seems broadly in line with EM and global peers.
KSA petchem firms set to post SR5bn net profit in Q4