
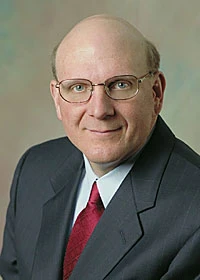
Microsoft will host 120 high-level government officials and business leaders from across the Middle East at the Government Leadership Forum (GLF) Arabia 2005, in Dubai on April 24-25. The two-day event, will bring together top government and business leaders from around the region with the goal of driving discussion around how the private ICT sector can work in cooperation with local, regional and central governments.
Sheikh Nahyan Bin Mubarak Al-Nahyan, UAE Minister of Education, and Microsoft’s CEO Steve Ballmer, along with a distinguished selection of experienced leaders from developed and developing nations in the region, will offer diverse viewpoints to enrich the dialogue at GLF. In addition, GLF will offer attendees access to lively, interactive panel discussions and an opportunity for peer networking and ad hoc discussion groups. In this way, the Microsoft Government Leaders Forum Arabia will enable important discussions between the ICT industry and the public sector.
Over the two days, GLF will present four dynamic discussion forums — “Growth and Economic Development,” “Governance and Modernization,” “Social Development and Education” and “Public/Private Partnership.”
Camera Phone Sales Surged in 2004
According to the latest research from Strategy Analytics, 257 million camera phones were shipped worldwide, representing 38 percent of total handset sales, in 2004. This was up sharply from 84 million, or 16 percent of total, in 2003. Camera phones outsold digital still cameras by almost 4 to 1, reaching just 68 million units globally in 2004. Sales grew 40 percent annually, from 49 million units in 2003.
“Global camera phone sales grew by an impressive 200 percent year-over-year in 2004,” said Neil Mawston, associate director of the Wireless Device Strategies (WDS) service at Strategy Analytics. “Nokia led the pack, with an 18 percent worldwide market share, followed closely by Motorola at 17 percent and Samsung in third position at 13 percent.”
Chris Ambrosio, director of Strategy Analytics’ Global Wireless Practice, added, “The digital still camera market is running out of steam. Vendors such as Kodak, Canon and Fuji will find growth harder to achieve in 2006. Camera phones will eventually capture 15 percent of the low-end digital still camera market by 2010, while attempts to sell households in developed markets a second or third device will be restricted by the ubiquity of multi-megapixel camera phones.”
Other findings from Strategy Analytics’ 2004 Global Camera Phone report include:
• VGA sensors will still be the sweet spot for camera phones in 2005, but vendors will use pixel counts as a differentiator in higher product tiers. These “Pixel Wars” will drive multimega-pixel handset demand to 3 in 10 sales worldwide in 2005;
• Removable memory will be standard issue on camera phones by the end of 2007 but the wireless connectivity landscape for camera phones (e.g. USB, WLAN/WiFi, Infrared, Bluetooth, etc.) will be fragmented, requiring printer, and other ecosystem players to support a wide range of solutions based on regional market dynamics.
UAE Leads Arab World in Connectivity Measures
A new report, “International Connectivity in the Arab World” was released by the Arab Advisors Group on March 31. The report shows that underlining its status as a major transit hub for voice and Internet traffic, UAE’s Etisalat is ahead of all Arab operators in terms of International voice circuits capacity and Internet bandwidth capacity. Saudi Arabia and Egypt, major Internet markets by all means, follow closely with each country having 16 percent of the total Internet capacity in the analyzed countries.
According to Arab Advisors, the transformation phase that Arab communication markets are witnessing promises to increase the demand for international connectivity in the short to medium timeframes. At present, most of Arab International Long Distance (ILD) communications markets are monopoly (de facto or de jure) markets (except for Algeria, Tunisia and Morocco), however liberalization plans are in advanced stages in many of the region’s countries.
Bahrain, for example, liberalized its telecom market in 2004, where fixed licenses (including international services) are expected to be granted by the Telecommunication Regulatory Authority during 2005. Jordan also began its market’s liberalization process at the beginning of this year. Up until March 16, two complete individual license applications, which allows setting up an ILD gateway, were submitted to the Telecommunication Regulatory Authority, these applications are currently in due process. Egypt, also, is expected to liberalize its fixed market in 2006, after Telecom Egypt’s monopoly license expires at the end of 2005. And Saudi Arabia’s two new data licensees both have international gateway rights.
These liberalization plans, and others that might not have such clear timelines, will undoubtedly lead to more bandwidth requirements (as new operators set up shop), and lower, cost-based rates once full competition is achieved. Tariff rebalancing, an essential prerequisite for liberalization, will result in reduced international service rates and will heighten demand for the service. High demand, especially with the increased uptake of high speed broadband Internet, will push operators onto obtaining greater international bandwidths from global operators such as FLAG and SEA-ME-WE.