
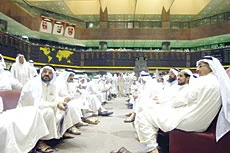
JEDDAH, 7 December 2004 — Kuwaiti equities rose to record levels in November driven by gains in services, insurance and banking sector stocks. The other remaining sectors also ended the month in positive territory, according to a report prepared by the Kuwait-based Global Investment House (GIH).
The market, as measured by the “Global” General Index, gained 4.85 percent in November. The Kuwait Stock Exchange is in a double-digit growth territory, up 12.27 percent to a new all-time high of 191.74 points, the report said.
The services sector led the advance, climbing 8.5 percent followed by insurance 7.7 percent and banking sector 7.1 percent during the month.
Services sector stocks have been buoyed by a steady stream of contract allotments, continued regional expansion and better than expected nine-month profitability.
Insurance companies, the GIH report said, which investors have been shying away from all year, saw renewed interest, driven by gains notched by Ahlia Insurance Co. (+22.2 percent), Warba Insurance Co. (+17.9 percent) and Gulf Insurance Co. (+3.6 percent).
The insurance sector however continues to underperform the market, still down 6.9 percent for the year.
Three of the four companies which have published results for the nine months of 2004 have registered improved profits, however, a 35.1 percent fall in the largest insurer Kuwait Insurance Co. has weighed on the sector’s total profitability.
Banks on the other hand have continued to benefit from the hardening of interest rates, with the latest rate hike occurring in November, bringing the discount rate to 4.5 percent. It is likely to help improve interest income for some banks, the report added.
Further, investors were positively influenced by the CBK’s decision to delay the implementation of the loan reserve ratio, which was originally scheduled for implementation in December 2004, to March 6, 2005. As a result, 7 of the 8 banks, Al Ahli Bank of Kuwait the exception, saw share prices climb higher.
The GIH report said a steady stream of new listings in the past few months has had its own intrinsic merits. New listings have helped improve the depth of the market, providing more choice to investors. Two companies were listed at the KSE during November; Commercial International Bank and Eyas for Higher Technical Education, bringing the total number of listed companies to 117.
Commercial International Bank was listed on Nov. 29, becoming the second cross-border listing to occur in 2004. This exhibits the strength and liquidity of the Kuwaiti market, as regional investors have exceedingly been eyeing both investing and listing opportunities at the market. Eyas was listed on the final day of the month in the services sector. Also during the month, the KSE Technical Committee initially approved the listing of five new companies at the KSE. Outside those companies and although no official comments have been made, First Takaful Insurance Co. and Nebrass Holding Co. are expected to list their shares in mid-December.
The implementation of new listing requirements by the KSE to help spur additional listings in the months to come, adding more depth and liquidity to the Kuwaiti market, the report said.
The market housed 59 advancing stocks, 41 decliners and 17 unchanged stocks by November end. The market produced KD1.27 billion in gains as the aggregate market cap breached the KD21 billion mark during the month, ending at KD21.4 billion.
Sultan Center Food Products Co. extended the rally which started in July. Within July-October period the stock gained 60 percent, adding another 57.9 percent during November alone. Trading on the counter was intense, as the volume of shares traded amounted to 139.5 million shares, or 7.6 percent of the total market volume. The steep price appreciation also placed it at the top of value leaders, with KD141.6 million changing hands in the month.
Gulf Bank was another major winner during the month, with its share value advancing by 38.1 percent. Fitch Ratings announced that Gulf Bank’s Long Term Credit Rating is maintained at A- and the Individual Rating is maintained at B/C with outlook as stable.
Gulf Bank’s net interest income improved by 22.9 percent to KD51.4 million in first 9 months as compared to the same period of the previous year. Buoyed by the improvement in the net interest income and strong growth in investment income, the net profit of the bank surged by 43.3 percent to KD54.4 million.
The Transport Group Co. (+23.9 percent), Metal Recycling Co. (+23.7 percent) and United Industries Co. (+22.9 percent) were other price leaders during the month, the GIH report added.
However, International Financial Advisors lost 10.98 percent during the month, despite being appointed as the state consultant in Residential Arifjan Project and announcing 9-month profit growth of 52.3 percent. Ahlia Investment Co. was another major decliner during the month, slipping 8.9 percent.
Other notable stocks which fell in November included Kuwait Foundry Co. (-8.7 percent), Automated Systems Co. (-7.3 percent) and Sharqa Cement Co. (-7.0 percent).
The holiday-shortened month consequently resulted in lower aggregate activity. Although the aggregate value of shares traded declined by 6.8 percent to KD1.1 billion during the month, the average daily value of shares traded improved to KD58.4 million as compared to KD54.2 million during October.
On the other hand, volume of shares traded fell once again to a new intra-year low, slipping below the 2 billion mark to 1.8 billion traded shares. The volume of shares traded has been steadily falling since August 2004.
Despite the steep gains during November, Kuwaiti equities still stand out from among their GCC peers for their low valuations. Kuwaiti shares have been the slowest in terms of price advances this year, following 2003’s boom. The market has been on a rebound since May, but even then, corporate earnings have continued to climb faster than share prices. The result has been Kuwait having a P/E ratio of 13.87, still below most of its peers. With prices still at affordable levels and the end of year earning season just around the corner, investors should prepare themselves for additional gains, as end of year profit expectations should continue to boost activity at the market through December and into 2005, the GIH report said.