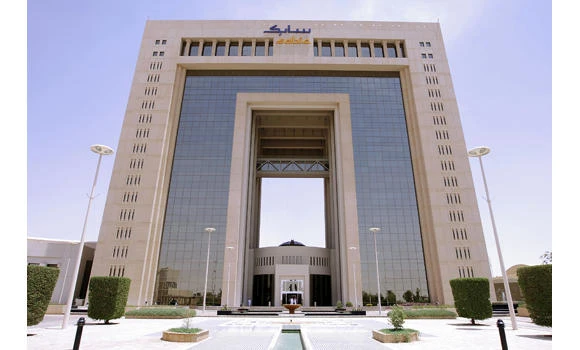
In its end-of-year update on the Saudi petrochemicals sector, NCB Capital, the GCC’s major wealth manager and the Kingdom’s “largest asset manager,” believes the Saudi petrochemical sector will be the main positive highlight for the Saudi market in 2014.
Iyad Ghulam, equity research analyst at NCB Capital, said: “We remain overweight on Saudi Basic Industries Corporation (SABIC), SIIG, Tasnee, Yansab and Advanced, while maintaining all other ratings. Higher petrochemicals’ prices driven by improved demand outlook, continued feedstock advantage, new start-ups and operational efficiency are expected to increase 2014 earnings by 21 percent YoY.
“We have revised petrochemical demand and price estimates higher for 2014 by an average 11 percent, driven by improving economic conditions in developed and emerging markets. Increasing industrial production, auto sales and housing market in the US and Europe is expected to continue to drive petrochemicals’ demand.
Moreover, the increase in Chinese exports is expected to mitigate the impact of any softening of the economy.
“We have delayed the expected change of feedstock prices from 2014 to 2015. The natural gas, which is supplied by Saudi Aramco at $0.75/mmbtu, was expected to double in 2014. However, no official announcement was made and therefore we postpone the increase to 2015. As a result, 2014 earnings estimates and valuations of most of the ten stocks under our coverage have been revised up by an average of 6 percent and 1 percent respectively due to this delay.”
NCB Capital remains overweight on SABIC, SIIG, Tasnee, Yansab and Advanced, and neutral on the remaining stocks under coverage. On average, the PTs are up 15 percent due to higher petrochemicals’ prices, operational efficiency, startups, and delay in revision of ethane prices.
“Our top picks are Tasnee and SIIG. Improved demand and pricing outlook for petrochemicals and TiO2 increase our confidence on Tasnee,” stated Ghulam. “While SIIG‘s valuation remains attractive driven by strong earnings from SCP/JCP, the startup of nylon 6.6 project and the increase in Petrochem’s earnings will support earnings growth.
NCB Capital expects the total net income of the ten stocks under coverage to increase by 21 percent YoY to SR42.5 billion in 2014, six percent higher than its previous estimate. The sector will benefit from higher demand, contribution from new projects and improved operational efficiency for most of the stocks under coverage.
SABIC: Higher prices to drive earnings
NCB Capital reiterates its overweight rating on SABIC with a revised PT of SR128.6. The expected improvement in demand and prices, delay in ethane price increase and the improved earnings outlook for Kayan and Yansab has led to a 7 percent increase in 2014 earnings estimates. The higher than expected dividends paid by Yansab and SAFCO also increase the possibility of higher dividends by SABIC going forward.
SAFCO: Lower earnings to impact dividends
NCB Capital remains neutral on SAFCO with a revised PT of 152.1. Lower fertilizer prices due to the change in global supply drivers are a key concern in the medium term. This could lead to lower dividends in 2014 and beyond, resulting in a pressure on the stock price. NCB Capital expects urea and ammonia prices to decline by around 6.1 percent and 12.4 percent respectively in 2014.
TASNEE: Start-ups and TiO2 to support 2014E growth
NCB Capital remains overweight on Tasnee with a revised PT of SR37.7. Improved demand and pricing outlook for petrochemicals and TiO2 increase the PT by 23.2 percent. Moreover, new projects are expected to support growth in the long run. With a 2014 P/E of 8.8x (a 33.2 percent discount to the sector), the stock represents an attractive investment opportunity at the current level.
YANSAB: Dividend growth story remains intact
“We remain overweight on Yansab with a revised PT of SR82.9,” said Ghulam. “We have revised higher our 2014 estimate by 9-10 percent due to improved demand and pricing outlook. Despite the impact of the shut down on Q4, 2013 results, we remain optimistic on Yansab’s ability to continue to pay higher dividends supported by strong 2014 FCF yield of 9.6 percent. We expect Yansab to pay a DPS of SR4 for 2014 indicating a payout ratio of 68.1 percent.”
Petrochemicals ‘to be main positive highlight for Saudi market in 2014’