
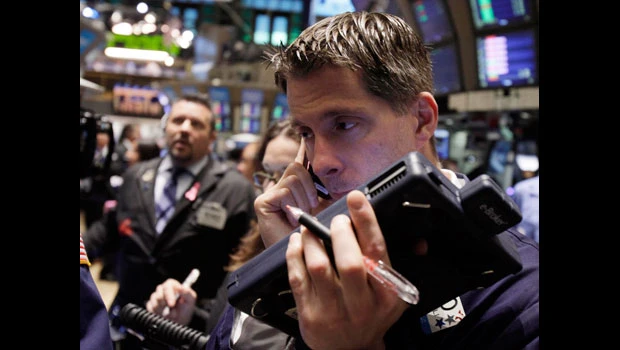
- NEW YORK: World stocks and the euro slumped on Wednesday as upheaval in highly indebted Greece and indecision among Europe’s leaders about helping the nation fed fears the euro zone member is edging closer to default.
The euro tumbled 2 percent against the dollar and government debt of the US and Germany rallied on a safety bid after euro zone finance ministers failed to agree on how to involve private investors in a second financial rescue for Greece.
Senior EU officials said a deal was now unlikely to be reached at a summit next week and was likely to be delayed until mid-July.
“It had looked like we were making progress on addressing Greece’s problems but now it seems things are fraying at the edges. People are capitulating, taking a defensive posture and getting out of their risky trades.” said George Davis, senior currency strategist at RBC Capital Markets in Toronto.
The dollar’s strengthening against the euro helped propel a more than 4 percent slide in the price of US crude oil, hurt also by further signs of economic weakness.
In the United States, dismal manufacturing and housing data intensified fears of slowing growth.
“There are plenty of things you can pick to be worried about,” said John Wilson, chief equity strategist at Morgan Keegan at Chattanooga, Tennessee. “You are seeing a capitulation and market sentiment is getting more negative.”
Investors recoiled at the latest developments less than 24 hours after they had tip-toed back into stocks and other risky assets. Wednesday’s flight out of growth-driven investments pushed the euro and US stock indexes down near key technical support levels.
Bank shares led the global sell-off after Moody’s Investors Service said it may put the credit ratings of French banks BNP Paribas, Credit gricoleand Societe Generale on review for a possible downgrade, citing the banks’ holdings of Greek public and private debt.
The rating agency later placed the ratings of some units of Portuguese banks in Brazil on review for possible downgrade.
The MSCI world stock index sagged 1.9 percent a day after posting its biggest single-day percentage
rise in two weeks due to less-grim economic data from China and the US.
On Wall Street, stocks erased Tuesday’s gains, which had temporarily slowed a six-week sell-off.
The Dow Jones industrial average closed down 178.84 points,or 1.48 percent, at 11,897.27. The Standard & Poor’s 500 Index ended down 22.45 points, or 1.74 percent, at 1,265.42. The Nasdaq Composite Index finished down 47.26 points, or 1.76 percent, at 2,631.46.
Top European shares lost 1.1 percent on the day, while Tokyo’s Nikkei ended 0.3 percent lower following Tuesday’s rally in New York.
As more evidence of an economic slowdown is likely to emerge, some analysts see a further decline in stocks.
“Even if it’s in a soft patch, the slope of the US recovery will still be disappointing and it will be an uneven performance,” said Clark Yingst, chief market analyst at Joseph Gunnar in New York.