RIYADH: Founders seeking venture backing in Saudi Arabia should not just position themselves in popular sectors for the sake of attracting funding, a leading investment firm official has warned.
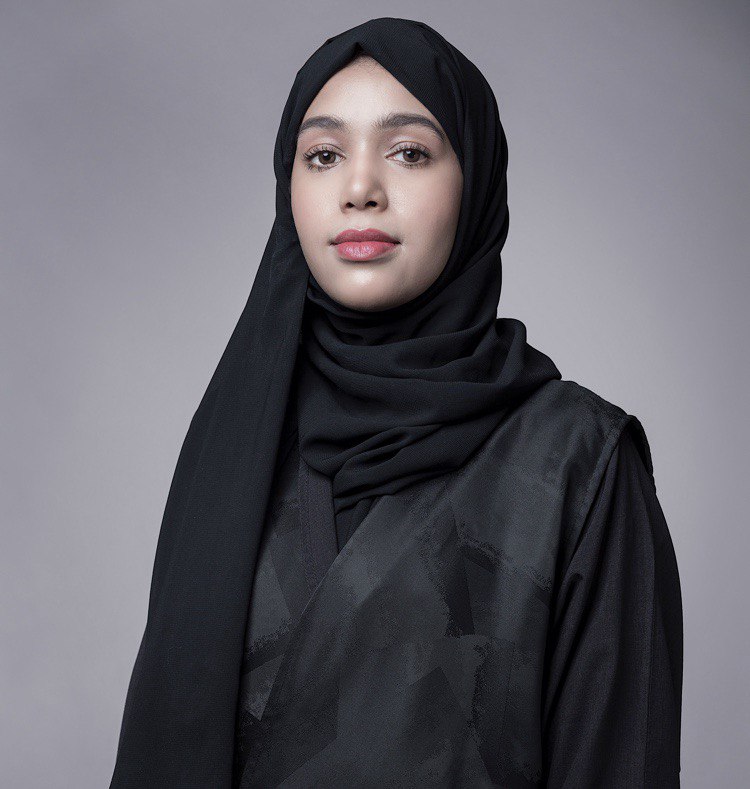
Latifa BaNasr, partner in Saudi investment firm Sharaka Capital, told Arab News that entrepreneurs should not rush towards the fintech or artificial intelligence spheres unless they are able to prove they understand an overlooked market problem and can build durable economics around it.
The concentration of Saudi venture funding helps explain why founders may gravitate toward fashionable categories.
A Saudi Venture Capital analysis covering 2018 to November 2025 found that fintech had attracted almost $4 billion, with payment solutions accounting for about 72 percent of the total.
MAGNiTT reported that fintech received 80 percent of capital deployed in the first quarter of 2026, even as gaming led by deal count.
“Don’t go for a category that is just big and attractive,” BaNasr said. “It’s preferable that you have an experience in it.”
She added that founder-market fit and market structure are also among Sharaka Capital's core considerations.
“What does the founder understand about that industry, that problem, that market that others don’t understand, including us?” BaNasr said.
Insight before category
The Sharaka Capital partner draws a distinction between market size and market structure. A large pool of spending with weak economics can be less investable than a smaller segment capable of expanding through pricing power, network effects or high switching costs, she said.
That means founders should look for neglected subsegments that can become markets in their own right.
In fintech, Sharaka considers payments and robo-advisory highly competitive, while its areas of interest include financial infrastructure and embedded finance.
The firm is also examining vertical Software-as-a-Service businesses, applied AI, cybersecurity, property technology and gaming monetization.
For AI companies, BaNasr said the technology must create a genuine moat rather than serve as “just a tag.”
Build a repeatable engine
Sector selection is only the starting point. BaNasr said founders must validate a sustainable and repeatable economic engine, showing that customers recognize enough value to remain with the product and potentially pay more as it develops.
“We want to see a product core or a technology that creates a measurable advantage and repeatable sort of economical engine that could strengthen over time, rather than something that would shrink over time,” she said.
For entrepreneurs, that shifts the fundraising case away from a broad total addressable market and toward evidence of defensibility: who holds pricing power, how regulation affects entry, whether customers face meaningful switching costs and why the business becomes stronger as it scales.
Learn faster than evidence changes
BaNasr said conviction is essential, but founders must not allow commitment to their vision to override contradictory evidence.
“We like resistance. However, what we don’t like is a founder who cannot see what reality is,” she said.
The quality she would most like to see in every early-stage founder is speed of learning, coupled with intellectual humility. That combination helps operators make difficult trade-offs, pivot into a better market, repair governance problems and recruit stronger talent, she said.
Experience is already becoming more visible in the Kingdom’s pipeline. An SVC report examining 400 Saudi founders found that 36 percent had more than 10 years of professional experience, supporting BaNasr’s observation that more serial entrepreneurs and former operators are entering the market.
Turn boards into working sessions
Some post-investment problems stem less from the product than from weak governance, the Sharaka Capital official said.
Boards can become forums for status reports, budget approvals and company updates when they should be identifying the most consequential problem and deciding how to tackle it.
Founders may also spend too much energy managing boardroom dynamics instead of extracting useful insight from directors.
Investors should diagnose whether the company needs a better board process, specialist coaching or targeted commercial support, she said.
They must also consider whether their own intervention created a new risk.
BaNasr cited the example of an investor introducing a major customer that later accounts for 60 percent of revenue. The sale brings growth, but also customer concentration that both sides must address.
Sharaka Capital does not typically lose conviction within six months when difficulties emerge, she added. At the early stage, worrying patterns may take two or three years to become clear, giving founders and investors time to investigate their cause and attempt a solution.
Learn in your biggest market
BaNasr said Saudi deal flow increasingly includes serial founders and former operators who have gained experience through both exits and failures.
She also sees an advantage in companies that begin in the Kingdom before expanding regionally or globally.
Building first in the company’s largest market gives founders direct exposure to local customers. A business developed elsewhere may arrive with assumptions shaped by different consumer behavior, requiring more capital and time to relearn the market, she said.
Sharaka Capital operates two venture funds, with its first fully deployed after it began investing in 2019 and its second launched in 2025.
The firm has invested in multiple companies so far and is actively seeking MENA founders raising seed or series A rounds, while also looking to engage growth-capital investors and companies developing liquidity or secondary-market solutions.