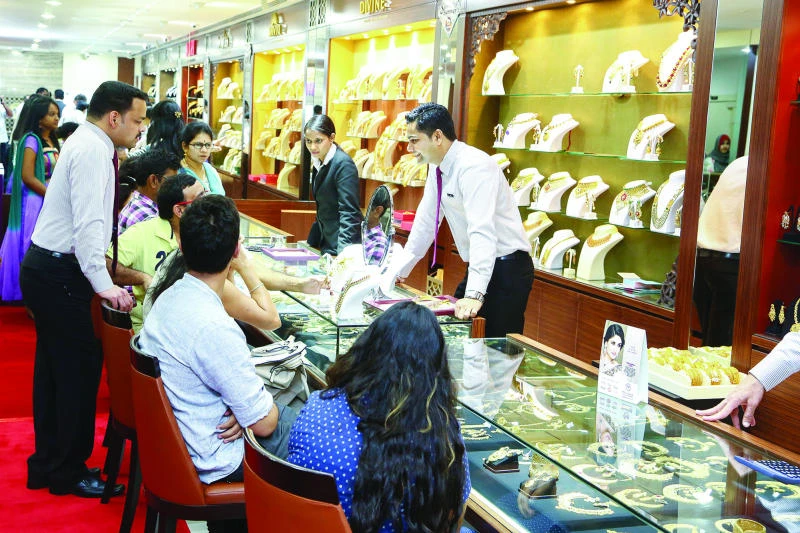
Malabar Gold and Diamonds, one of the world’s largest gold and diamond retailers, will open 21 retail stores across the GCC, India and the Far East in the next six months with an investment outlay of AED460 million ($125 million).
Of the total, Malabar Gold and Diamonds is investing AED223 million in eight stores in the UAE, AED100 million in five outlets in Saudi Arabia, AED57 million in three outlets in Oman, and AED20 million in one outlet in Malaysia.
In addition to these, the company will add four more outlets in India at an investment of AED60 million.
The expansion will see the gold and diamond jewelry retailer expand its retail network from 134 to 155 — reinforcing its position as the most preferred jeweler in the world. The move also reflects the fastest growth by a jewelry retail chain in the world – emerging from being a small player to being among the top 5 jewelry retailers worldwide within a decade.
“The current lower gold and commodity prices offer a great opportunity for investors and jewelry buyers,” M.P. Ahamed, chairman of Malabar Group, says.
Philippe Mellier, chief executive of De Beers Group, said: “As the number of middle class households in the major consumer markets is set to grow by hundreds of millions in the years ahead, the medium to long term prospects for the diamond industry are also exceptionally strong.”
Shamlal Ahamed, MD of international operations at Malabar Gold and Diamonds, said: “With consumer demand growing by the day, we feel the need to offer greater space, design, collections and options to our customers.”
Abdul Salam KP, group executive director of Malabar Group, said: “We are upbeat about the oncoming six months due to the key festive and holiday seasons."
sponsored
Malabar Gold and Diamonds invests $125m in 21 outlets